Blog

  • Foreign Transaction Fees Explained: Pay in Dollars for Less

    Foreign Transaction Fees Explained: Pay in Dollars for Less

    Example scenario: you pay $30 a month for an AI tool, $15 for a design app and $12 for cloud storage, all billed in US dollars. Your card is in your local currency. Each month the statement shows three charges, each a little higher than the dollar price would suggest, plus three small “foreign transaction fee” lines underneath. None of it looks like much on its own. Over a year, across every subscription and online purchase in dollars, it adds up to a real amount you never chose to pay.

    A foreign transaction fee is only one part of the cost of paying in another currency. This guide explains each part, shows where it appears, and covers the practical ways to pay in dollars (or any foreign currency) for less, including holding a balance in the merchant’s currency.

    What is a foreign transaction fee?

    A foreign transaction fee is a charge your card issuer adds when you make a purchase in a foreign currency, or in some cases with a merchant based abroad even if it charges you in your own currency. It is usually a percentage of the purchase. Many card issuers charge somewhere between 1% and 3%, while some cards charge nothing. The exact rate is in your card’s terms or fee schedule.

    The three layers of cost

    When a card in one currency pays in another, you can pay for the conversion in up to three ways:

    1. The exchange rate itself

    Your card network converts the amount at its own rate. That rate is usually close to the market rate, but it is not always the rate you see on a currency website, and it can move between the day you buy and the day the charge settles.

    2. The issuer’s foreign transaction fee

    Your issuer adds its fee on top, often shown as a separate line on your statement and sometimes folded into the converted amount.

    3. Dynamic currency conversion (DCC)

    Some merchants and payment pages offer to charge you in your home currency instead of their own. That conversion is done at a rate the merchant or its provider sets, and it often includes a markup. Your issuer may still add its own fee if the merchant is abroad. Visa’s consumer guidance on dynamic currency conversion says merchants must show both amounts, the exchange rate and any markup, and must let you choose rather than choosing for you.

    A worked example

    The figures below are illustrative assumptions, not real rates. They show how the layers stack on a $100 purchase paid from a card in another currency.

    ScenarioWhat happensCost on top of the market rate (illustrative)
    Pay in USD with a card that has no foreign feeNetwork rate onlyA small exchange margin
    Pay in USD with a card that charges a 3% feeNetwork rate plus issuer feeAbout 3%, plus the exchange margin
    Accept DCC on the same cardMerchant’s rate with markup, and the issuer fee may still applyThe DCC markup, plus up to 3%
    Pay from a balance already held in USDNo conversion at the time of purchaseOnly whatever it cost to get the dollars onto the card

    The last row is the key idea. If you already hold the merchant’s currency, the purchase itself involves no conversion. You pay for conversion once, when you load the money, and you can compare that cost before you do it.

    How to find out what you pay now

    1. Read your card’s fee schedule. Look for “foreign transaction fee”, “cross-border fee” or “currency conversion fee”.
    2. Check a recent foreign purchase on your statement. Note the original amount, the converted amount and any separate fee line.
    3. Compare with the market rate for that day. The gap between the market conversion and what you paid is your total conversion cost.
    4. Add it up for a year. Multiply your monthly foreign spending by the percentage you found. That is the number worth reducing.

    Ways to pay less

    Use a card with no foreign transaction fee

    Some credit and debit cards charge no foreign fee. If you can get one in your country, it removes the issuer layer, though the network exchange rate still applies.

    Always decline DCC

    When a checkout offers to charge you in your home currency, choose the merchant’s currency instead. This avoids the DCC markup. It is the simplest saving on this list.

    Hold a balance in the merchant’s currency

    If you pay many merchants in one currency, holding that currency means each purchase is paid without converting. Two common ways to do this:

    • A multi-currency account such as Wise or Revolut lets you convert into dollars in one step and spend the dollar balance with a card. Each provider publishes its own conversion fees, and availability depends on your country.
    • A prepaid card in the merchant’s currency holds a fixed balance, for example in USD, and spends it directly on dollar-billed merchants.

    Either way, you are trading many small conversions for one. That only saves money if the one conversion is cheaper, so compare it.

    Compare the funding cost honestly

    Before you move money onto a foreign-currency balance or card, add up everything it costs to get there: the exchange rate you receive, any transfer or withdrawal fees, and any card issue or top-up charge. Then compare that total with your current card’s foreign fee on the same amount. Sometimes the existing card wins, especially for small or occasional purchases.

    Example: holding dollars on a Vizovcc card

    Vizovcc sells prepaid virtual cards, including US-issued Visa and Mastercard cards that hold a USD balance, as well as cards in other currencies. You add crypto to an account balance and buy a card from it. Each card page shows a fixed price in USD and how it splits between the card issue charge and the balance loaded onto the card. Some cards also list a $0.10 fee on international transactions, so check the card page.

    To judge whether this lowers your cost, follow the comparison above rather than assuming it does:

    • Funding cost: what it costs to get crypto into the account (exchange spread and any withdrawal fee from your exchange), plus the card issue charge shown on the card page.
    • Per-charge cost: paying a USD merchant from a USD card involves no conversion at the time of purchase, though a card’s listed international fee may apply.
    • Your current cost: your bank’s foreign transaction fee and exchange margin on the same yearly spending.

    If you pay a steady set of dollar subscriptions, one funded USD card can replace a month of small conversions. If you only buy in dollars occasionally, your existing card may be cheaper. Other practical points: Vizovcc funding is crypto only, any merchant can decline a prepaid card, and card purchases are final, so choose the card and currency carefully. Vizovcc explains how funding a card from crypto works step by step.

    FAQ

    Why was I charged a foreign transaction fee on a purchase in my own currency?

    Some issuers charge a cross-border fee when the merchant or its payment processor is located abroad, even if the price is in your currency. Check your card’s terms for “cross-border” wording.

    Is DCC ever worth accepting?

    It gives you certainty about the amount in your home currency, but the rate usually includes a markup. If cost matters, choose the merchant’s currency.

    Do prepaid cards have foreign transaction fees?

    Some do and some do not. It depends on the provider and the card, so check the fee details before buying.

    Key takeaways

    • A foreign transaction fee is the issuer’s charge on foreign purchases, often between 1% and 3%, and some cards charge none.
    • The exchange rate and DCC markups add to the total cost.
    • Always choose the merchant’s currency when offered DCC.
    • Holding a balance in the merchant’s currency replaces many conversions with one.
    • Compare the cost of funding that balance with your current card’s fees before switching.

    Pull up last month’s statement and work out what your foreign charges really cost. If a USD balance looks like the cheaper route for your subscriptions, compare the card pages at Vizovcc against your bank’s fees and decide with the numbers in front of you.

  • Best Virtual Cards for Google Ads and Meta Ads Billing

    Best Virtual Cards for Google Ads and Meta Ads Billing

    Disclosure: this article was written for ZenVCC, which appears as one of the picks below. Details for every provider were checked on each provider’s own website in November 2026. Fees and features change, so confirm them before you sign up.

    Picture a Friday evening launch (an example, not a real account). A new Meta campaign is pacing well, then the ad account shows a failed payment and delivery stops. The card was fine on Tuesday. It hit a billing threshold, the issuer flagged an unusual charge, and nobody will see the alert until Monday. Meanwhile the Google Ads account billed to the same card fails its next charge too.

    Choosing the best virtual card for Facebook ads and Google Ads is less about finding a magic card and more about matching a card to how each platform bills, which cards it accepts, and how much control your team needs. This guide explains the billing rules that matter, compares four providers on the points media buyers care about, and gives you a framework for picking one.

    How Meta and Google bill your card

    Meta Ads

    Most Meta ad accounts use automatic payments: Meta charges the card when spend reaches a billing threshold and again on the monthly billing date. Accepted cards vary by country, but Meta’s list of accepted payment options includes credit cards and co-branded debit cards from American Express, Mastercard and Visa in most markets, plus PayPal in supported currencies. Meta can still decline a specific card for a specific account.

    Google Ads

    Google offers automatic payments (postpay), where it charges after ads run, and manual payments (prepay) in some countries, where you add money first. The detail that catches many advertisers out: Google’s overview of billing options states that it no longer accepts prepaid cards for postpay. If you plan to use a prepaid card on Google, you need the manual setting where it is offered, and Google decides per account what it accepts.

    Why this shapes your card choice

    Both platforms charge frequently and without warning. Any card you choose has to cope with many charges a month, in the ad account’s currency, without tripping the issuer’s own fraud checks. A decline usually pauses delivery until a payment goes through.

    What to judge a card on

    • Platform fit. Is it a credit, charge, debit or prepaid card, and does that type work with the billing setting you use on each platform?
    • Billing currency. A card in the ad account’s currency avoids a conversion on every charge.
    • Controls. Can you hold many cards and set limits or merchant restrictions on each one?
    • Costs at scale. Count monthly fees, per-card fees and foreign transaction fees across every card you will hold.
    • Eligibility and funding. Some cards need a US company, a bank account with the provider or a credit review. Others are funded in advance.
    • Rewards. Cashback is useful on large budgets, but it should never outweigh reliable payments.

    Comparison table

    ProviderCard typeFunding and eligibilityControlsFees noted on its site
    SlashVisa charge card (issued by Column N.A.)Settles daily from a Slash cash account; built for verified US businessesUnlimited virtual cards, per-card limits and merchant restrictions$0 Free plan or $25 a month Pro; cashback on eligible spend
    Mercury IOMastercard charge cardMercury account holders only; limit based on balancesVirtual and physical cards for team membersNo annual fee; 1.5% cashback; a fee on non-USD transactions
    Wise BusinessDebit cardSpends from a multi-currency Wise Business accountDefault and maximum limits per card, person or groupOne-time setup fee ($31 on the US site); conversion fees vary by currency
    ZenVCCPrepaid virtual Visa, Mastercard, Amex or MaestroOne balance funded with crypto; identity check may be requiredSeparate card per ad account; prepaid balance is the ceiling$10 one-time issue fee per card, $0.10 per payment, no monthly fee

    The picks

    Slash: for US agencies that want cashback and detailed card controls

    Slash offers a Visa charge card with unlimited virtual cards, and its site says each card can carry its own monthly limit, per-transaction ceiling and merchant restriction. Charges settle from your Slash cash account each business day, so it behaves like spending your own deposits rather than borrowing. It suits US-registered agencies running several ad accounts that want controls set per card.

    Mercury IO: for startups already banking with Mercury

    Mercury’s IO card is a Mastercard charge card with 1.5% cashback and no annual fee. It is only for Mercury account holders, and the spending limit depends on the balances you hold. If your company already banks with Mercury and spends mostly in USD, it is a simple option. Note the fee on non-USD transactions if your ad accounts bill in other currencies.

    Wise Business: for teams paying ads in several currencies

    Wise Business issues debit cards that spend from a multi-currency account in 40+ currencies, with limits you can set per card, person or group. That makes it a fit for teams with ad accounts billing in EUR, GBP and USD at once. As a debit card, it falls into the co-branded debit category Meta lists in most markets, though acceptance is still decided per account.

    ZenVCC: for prepaid, per-account cards without a monthly fee

    This pick takes a different approach. It is a prepaid virtual card platform, not a bank, so there is no credit review and no credit line. You fund one balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), each deposit is checked on its blockchain, and you buy a separate card for each ad account from that balance. Its catalog of about 49 cards covers Visa, Mastercard and American Express, plus country cards such as Turkish lira cards for accounts that bill locally.

    The costs are fixed and easy to forecast: a $10 issue fee per card, $0.10 per payment and no monthly fee, with cards valid for three years from the day they are ready. If a card cannot be prepared, the full amount returns to your balance. There are trade-offs. It sets no per-card limits or merchant locks; the prepaid balance is the cap and budgets are set inside each ad platform. Because the cards are prepaid, Google postpay is not an option, and cards cannot be topped up from the dashboard. You can see the supported platforms on ZenVCC’s cards for advertising payments page, which lists Meta, Google, TikTok, Microsoft Advertising, LinkedIn and others.

    A five-step framework for choosing

    1. Map your accounts. List each ad account with its platform, billing setting (automatic or manual) and currency.
    2. Rule out mismatches. If an account must use Google postpay, rule out prepaid cards for it. If an account bills in EUR, favor a card that holds EUR.
    3. Check eligibility. Charge cards and corporate cards usually need a registered company and a review. Prepaid cards need funding up front.
    4. Decide where controls live. If you want limits on the card itself, pick a provider that offers them. If budgets already live inside Meta and Google, a prepaid balance may be enough.
    5. Test before you scale. Add one card to one account, run a small payment, and move full budgets only after a clean billing cycle.

    Platform policies still apply

    A card is a payment method, not a policy tool. Every ad account still has to follow Meta’s and Google’s advertising and payment policies, billing details should match the card exactly, and no card provider can guarantee that a platform will accept its cards. Using new cards to get around a disabled account, a review or a spending restriction breaks platform rules and puts every connected account at risk.

    Key takeaways

    • Meta and Google both charge cards automatically and often, so reliability matters more than rewards.
    • Google does not accept prepaid cards for postpay billing; plan the billing setting before you choose a card.
    • Charge cards like Slash and Mercury IO suit US companies with banking in place; Wise suits multi-currency teams.
    • Prepaid cards suit teams that want one card per account, fixed costs and no credit review.
    • Test each new card with a small payment before moving a full budget onto it.

    Start by mapping your accounts and billing settings this week; the right card usually becomes obvious once you can see them side by side. If a prepaid card per ad account fits your setup, compare the costs at ZenVCC with the other options above.

  • Why Businesses Choose Professional Corporate Transfers

    Why Businesses Choose Professional Corporate Transfers

    Elegant Charters, a Perth-based chauffeur and passenger transport provider, is highlighting its corporate transfer services for businesses seeking reliable and professionally coordinated ground transportation. The service is designed to support business meetings, airport pickups, corporate events and other work-related travel across Perth and surrounding areas.

    As businesses manage increasingly varied travel requirements, arranging dependable transportation has become an important consideration for employees, executives, visiting clients and corporate guests. Punctual arrivals, comfortable vehicles and flexible scheduling can help organisations coordinate their travel arrangements more efficiently.

    Addressing the Challenges of Business Travel

    Corporate travel often involves multiple destinations, changing schedules and passengers with different transportation requirements. Airport transfers, business meetings, conferences and executive appointments can require careful coordination, particularly when employees or visiting clients are unfamiliar with local routes.

    Relying on last-minute transport arrangements can also create logistical difficulties. Businesses may need vehicles that accommodate individual passengers, small teams or larger corporate groups while maintaining consistent service standards.

    Elegant Charters’ Response to Corporate Transportation Needs

    Elegant Charters provides chauffeur-driven transportation and private transfer options designed to accommodate a range of corporate travel requirements in Perth.

    The company’s vehicle fleet includes sedans, SUVs, 4–7-seater vehicles and 13–24-seater minibuses and maxi cabs. This range allows businesses to arrange transportation for individual executives, visiting professionals, small teams and larger groups.

    Through its online booking platform, Elegant Charters offers customers access to booking arrangements and quote requests at any time. Its services are intended to support scheduled business journeys as well as airport pickups and transfers requiring flexible coordination.

    Corporate Transfer Services and Transport Options

    Elegant Charters’ transportation services cover several business-related travel requirements, including:

    • Corporate transfers: Private transportation for business meetings, appointments and professional engagements.
    • Executive chauffeur services: Chauffeur-driven travel for executives, business visitors and corporate guests.
    • Airport transfers: Transportation to and from Perth Airport for employees, clients and visiting business representatives.
    • Corporate events: Group transportation for conferences, business functions and professional gatherings.
    • Group transportation: Minibuses and maxi cabs accommodating larger passenger groups.
    • Long-distance transfers: Pre-arranged journeys for business travel beyond metropolitan Perth.

    The company also offers personalised travel arrangements, flexible payment options and 24-hour booking availability. These options provide businesses with additional flexibility when coordinating transportation around different schedules and passenger requirements.

    Why Businesses Choose Professional Corporate Transfers

    Professional corporate transfers offer several practical considerations for organisations managing employee and client transportation.

    Additional details are available at: https://share.google/FSAdcLsUiOwdP7pXf

    A pre-arranged transfer can help reduce the uncertainty associated with finding transportation at busy airports or unfamiliar locations. Chauffeur-driven vehicles also provide passengers with an opportunity to travel between appointments without having to manage parking, navigation or vehicle arrangements themselves.

    For organisations hosting visiting executives or clients, professionally arranged transportation can contribute to a more coordinated arrival experience. Businesses transporting teams to conferences, corporate functions or other group activities can also benefit from vehicles suited to their passenger numbers.

    Vehicle selection, scheduling flexibility and advance booking arrangements remain important factors when choosing a corporate transport provider.

    Supporting Business Travel Across Perth

    Based in Southern River, Western Australia, Elegant Charters serves customers requiring transportation across Perth and surrounding areas. Its broader service offering includes airport transfers, weddings, tours, hotel transfers, cruise transportation, FIFO transfers and family travel.

    The company also provides baby-seat options for eligible family transportation requirements, alongside a selection of vehicles designed for different passenger capacities.

    By combining chauffeur services, private transfers and group transportation, Elegant Charters aims to accommodate a variety of passenger travel needs through one booking provider.

    Executive Comment

    An authorised spokesperson for Elegant Charters said:

    “Business transportation requires careful attention to scheduling, passenger comfort and coordination. Our range of vehicles and transfer options is designed to accommodate different corporate travel requirements, from individual airport pickups to transportation for larger business groups. We aim to make arranging professional transport across Perth straightforward and accessible.”

    Looking Ahead

    As business travel requirements continue to evolve, flexible ground transportation remains an important part of corporate travel planning. Elegant Charters intends to continue supporting Perth businesses and professional travellers through its range of chauffeur-driven vehicles, airport transfers and group transportation services.

    Businesses seeking corporate transfers in Perth can review available services, request a quote and arrange bookings through the company’s website.

    About Elegant Charters

    Elegant Charters is a Perth-based passenger transportation and chauffeur service provider located in Southern River, Western Australia. The company offers airport transfers, corporate transportation, chauffeur services, private taxi services, group transfers, tours, wedding transportation and long-distance travel.

    Its fleet includes sedans, SUVs, 4–7-seater vehicles and 13–24-seater minibuses and maxi cabs. Elegant Charters provides 24-hour online booking access, quote requests, flexible payment options and personalised travel arrangements for individuals, families, corporate customers and groups.

    Media Contact

    Elegant Charters
    Southern River, WA, Australia
    Phone: +61 458 655 640
    Website: https://elegantcharters.com.au/

  • Valentine Services – Stump Grinding Introduces Professional Wood Chip Removal in Cincinnati, Ohio

    Valentine Services – Stump Grinding Introduces Professional Wood Chip Removal in Cincinnati, Ohio

    Valentine Services – Stump Grinding has announced the addition of professional wood chip removal services for residential and commercial properties throughout Cincinnati, Ohio, and Northern Kentucky. The new service expands the company’s existing stump grinding and removal capabilities by providing property owners with an additional option for managing leftover wood chips following stump removal projects.

    Wood chips are a common byproduct of stump grinding. Although some property owners choose to reuse the material as landscape mulch, others prefer to have the remaining debris removed to maintain a cleaner and more accessible outdoor space. Managing accumulated wood chips can be particularly important for properties preparing for landscaping, lawn restoration, construction, or other improvement projects.

    Valentine Services introduced the wood chip removal service in response to the cleanup needs associated with stump grinding work. By incorporating wood chip removal into its service offerings, the company aims to provide customers with a more complete approach to managing the aftermath of unwanted stump removal.

    Addressing Property Cleanup Needs

    Stump grinding can leave behind a mixture of wood chips, sawdust, and organic debris. Depending on the size of the stump and the surrounding conditions, the resulting material may occupy a significant portion of the work area.

    For homeowners, businesses, property managers, and contractors, removing excess wood chips can help prepare outdoor spaces for their next intended use. Professional cleanup can also reduce the amount of manual work required after a stump grinding project.

    Expanded Services From Valentine Services

    Valentine Services – Stump Grinding provides stump grinding and stump removal solutions for properties throughout the Greater Cincinnati area and Northern Kentucky.

    Its service offerings include residential stump grinding, commercial stump grinding, surface root grinding, large stump removal, chip cleanup, and site restoration. The addition of wood chip removal further supports customers who need assistance addressing the debris left behind during stump grinding projects.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    The company works with homeowners, commercial property owners, property managers, and contractors seeking practical solutions for unwanted tree stumps and related ground-level hazards.

    Service Availability Across Greater Cincinnati

    Valentine Services serves Cincinnati and surrounding communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, and Hebron.

    The company is licensed and insured and provides free estimates for customers evaluating stump grinding and related property cleanup services.

    Company Perspective

    “Wood chips are a natural part of the stump grinding process, but not every property owner wants to keep that material on their property. Adding wood chip removal gives customers another option for addressing the cleanup that follows stump grinding,” said a company representative.

    Note: This is a proposed executive quote and should be approved by the company before publication.

    Supporting Cleaner Outdoor Spaces

    As property owners continue to improve residential landscapes and commercial outdoor spaces, services that address both stump removal and the resulting debris can play an important role in project preparation.

    Valentine Services – Stump Grinding plans to continue serving the Greater Cincinnati and Northern Kentucky markets with stump grinding, root removal, and related cleanup solutions designed to address a range of property needs.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company serves residential and commercial customers, property managers, and contractors with services that include stump grinding, root grinding, large stump removal, chip cleanup, wood chip removal, and site restoration. Licensed and insured, Valentine Services offers free estimates and serves communities throughout the Greater Cincinnati region and Northern Kentucky.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: https://www.513stumps.com/

  • How to Vet a Crypto Virtual Card Provider Before You Deposit: 12 Red Flags From Real Complaints

    How to Vet a Crypto Virtual Card Provider Before You Deposit: 12 Red Flags From Real Complaints

    You found a site that turns USDT into a virtual Visa in minutes. The design looks professional and the fees look fair. But once your stablecoins leave your wallet, you can’t take them back, so you need to know before you send whether this provider will still answer you next month.

    Quick answer

    1. Spend 15 minutes on the 12 checks below before you deposit anything.

    2. Then run a small test: deposit a small amount, make one purchase, and withdraw the rest.

    3. Any provider that fails the support, withdrawal or company-identity checks does not get a large balance, however good the fees look.

    Why vetting comes before the deposit

    A card payment can be disputed. A stablecoin transfer can’t. Once USDT or USDC lands at a provider’s deposit address, getting it back depends entirely on that provider’s process and goodwill. Your leverage is highest before you send, and it drops to almost nothing after.

    User reviews of crypto card providers on Trustpilot, read for this article, repeat the same three complaints across several services:

    • Deposits “rejected without explanation.” The coins were sent, the balance never appeared, and no reason was given.
    • Withdrawals stuck for weeks. Reviewers describe waiting 14 days or more for unspent balances.
    • Support that goes silent. Telegram or WhatsApp chats that stop replying once a problem appears.

    These are user reports, not findings against any one company. Some reviews describe user error, and some providers resolve the issues later. But the patterns tell you what to test. Each red flag below maps to one of these failures.

    The 12 red flags

    Support and contact

    1. Support handles that don’t match the brand. If a site called “ExampleCard” links to a Telegram account with a different name, you can’t tell whether it is a rebrand, a reseller or an impersonator. Every official channel should carry the brand’s name.

    2. Placeholder or dead contact details. Click every contact link on the site. A WhatsApp link to an obviously fake number, an email that bounces, or a contact form that never replies means nobody has checked the support path a customer would use.

    3. Chat-only support with no paper trail. Telegram and WhatsApp are convenient, but they leave no ticket number. Look for an email address or ticket system as well, so a dispute has a record.

    Who holds your money

    4. No named company and no named card issuer. A virtual Visa or Mastercard is issued by a regulated issuer, often through a program manager. If the site names neither the operating company nor the issuer, you can’t check either one. “We are not a bank” is an honest statement. It still leaves the question of who is.

    5. Fees you can only see after depositing. Issue fee, top-up fee, monthly fee, withdrawal fee and currency conversion should all be on a public page before signup.

    6. No published limits. Monthly spending limits, minimum deposits and maximum balances belong on the pricing page. Limits that appear only after you deposit become a reason to hold your funds.

    Deposits and withdrawals

    7. No clear way to get unspent money back. Look for a documented withdrawal route: to which wallet, on which networks, with what fee and in what timeframe. This is the single most important check, because stuck withdrawals are the most damaging complaint in the reviews.

    8. A vague or contradictory deposit process. If one page says deposits credit automatically, another asks for a screenshot, and a third asks for a transaction hash, ask which is true before you send. Contradictions are where “rejected without explanation” starts.

    Marketing claims

    9. “Works everywhere” or “guaranteed approval.” No card works everywhere. Merchants and platforms run their own checks, and some refuse prepaid cards by policy. Google Ads, for example, does not accept prepaid cards for postpay billing. An honest provider tells you where its cards are declined.

    10. “No KYC” or “anonymous” as the headline. Card issuers are regulated, and identity checks are a normal part of that. A provider that sells itself on avoiding checks is either describing something it can’t sustain or something you should not use.

    11. Missing or copied policies. Look for terms of service, a privacy policy and an AML policy. Paste one distinctive sentence into a search engine. If the same terms appear word for word under another brand’s name, treat that as a warning.

    12. Pressure and too-fast promises. Bonuses for larger first deposits, countdown timers and promises that every deposit credits immediately are sales tactics, not safety features. Responsible services check deposits before crediting them. And nobody genuine will ever ask for your seed phrase or private key.

    The 15-minute vetting table

    #CheckWhere to lookPass looks like
    1–3Support channelsContact page, site footer, chat widgetBrand-named handles, working links, an email or ticket option
    4Company and issuerAbout page, terms, card detailsA named legal entity and card issuer you can look up
    5–6Fees and limitsPricing pageEvery fee and limit visible before signup
    7WithdrawalsHelp pages, terms, dashboardA documented route back to your wallet
    8Deposit processHelp, FAQ, pricing pagesOne consistent description everywhere
    9–10Marketing claimsHome page, adsPlain limits stated; no “guaranteed” or “no KYC” pitch
    11PoliciesFooter linksTerms, privacy and AML policies written for this brand
    12Sales pressureHome page, onboardingNo deposit bonuses, timers or requests for keys

    Then read the 1- and 2-star reviews on independent review sites. Look past the star rating to the pattern: are the complaints about the same failure, recent, and answered with something more useful than a template reply?

    The small-deposit test

    Passing the checklist earns a test, not your full balance.

    1.  Deposit a small amount you could afford to lose, on the network the provider lists. Copy the address from the dashboard, never from a chat message.

    2.  Time the credit. Note when you sent the coins and when the balance appeared. If it didn’t, contact support and see how they handle it.

    3.  Issue a card and make one small, real purchase at a merchant you already use.

    4.  Ask support one question through the official channel, and note how long a useful answer takes.

    5.  Withdraw the remaining balance to your wallet. This is the step most people skip, and the one that matters most.

    6.  Only then decide whether to deposit more, and keep the balance close to what you plan to spend.

    Applying the checklist: one worked example

    Here is how the checks look on one provider. VCCBuy’s About page and the pages linked from it cover several items. Card fees and monthly limits are published on the pricing page. The site states that it is not a bank and publishes an AML policy. Unspent balance can be withdrawn to a crypto wallet. Deposits are described as checked before they are credited. The remaining checks, including support channels, company and issuer details and the small-deposit test, are yours to run here exactly as you would anywhere else. No provider, VCCBuy included, should be exempt from them.

    Alternatives deserve the same scrutiny. Bank-issued virtual cards and established fintech accounts usually pass the identity checks easily, but they may not accept crypto funding at all.

    Checklist to save

    ☐  All support links work and carry the brand’s name

    ☐  An email or ticket channel exists alongside chat

    ☐  Operating company and card issuer are named

    ☐  Fees and limits are public before signup

    ☐  Withdrawal route is documented

    ☐  Deposit process is described the same way on every page

    ☐  No “works everywhere”, “guaranteed” or “no KYC” claims

    ☐  Terms, privacy and AML policies exist and are not copied

    ☐  No deposit bonuses, countdowns or requests for keys

    ☐  Recent reviews checked for repeated failures

    ☐  Small-deposit test completed, including a withdrawal

    FAQ

    Is a provider with bad Trustpilot reviews always a scam? No. Review sites attract complaints, and some describe user mistakes such as sending coins on the wrong network. Look for patterns: the same failure, repeated recently, with no real resolution from the company.

    Why does it matter who the card issuer is? The issuer is the regulated party in the card network, and its status affects what happens to balances if the program changes or closes. If you can’t identify it, you can’t assess that risk.

    How much should I keep on a crypto card? Keep only what you plan to spend in the near term. Lean balances limit the damage from a stuck withdrawal, a frozen program or a compromised account.

    Conclusion

    The best time to find out how a crypto card provider behaves is before it holds your money. Run the 12 checks, do a small deposit, and test the withdrawal first. Whichever provider you choose, VCCBuy or another, keep the balance lean and the paper trail complete.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write provider-neutral safety guides for people funding cards with crypto.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP Cloud Platform Integration for S/4HANA Integration

    SAP Cloud Platform Integration for S/4HANA Integration

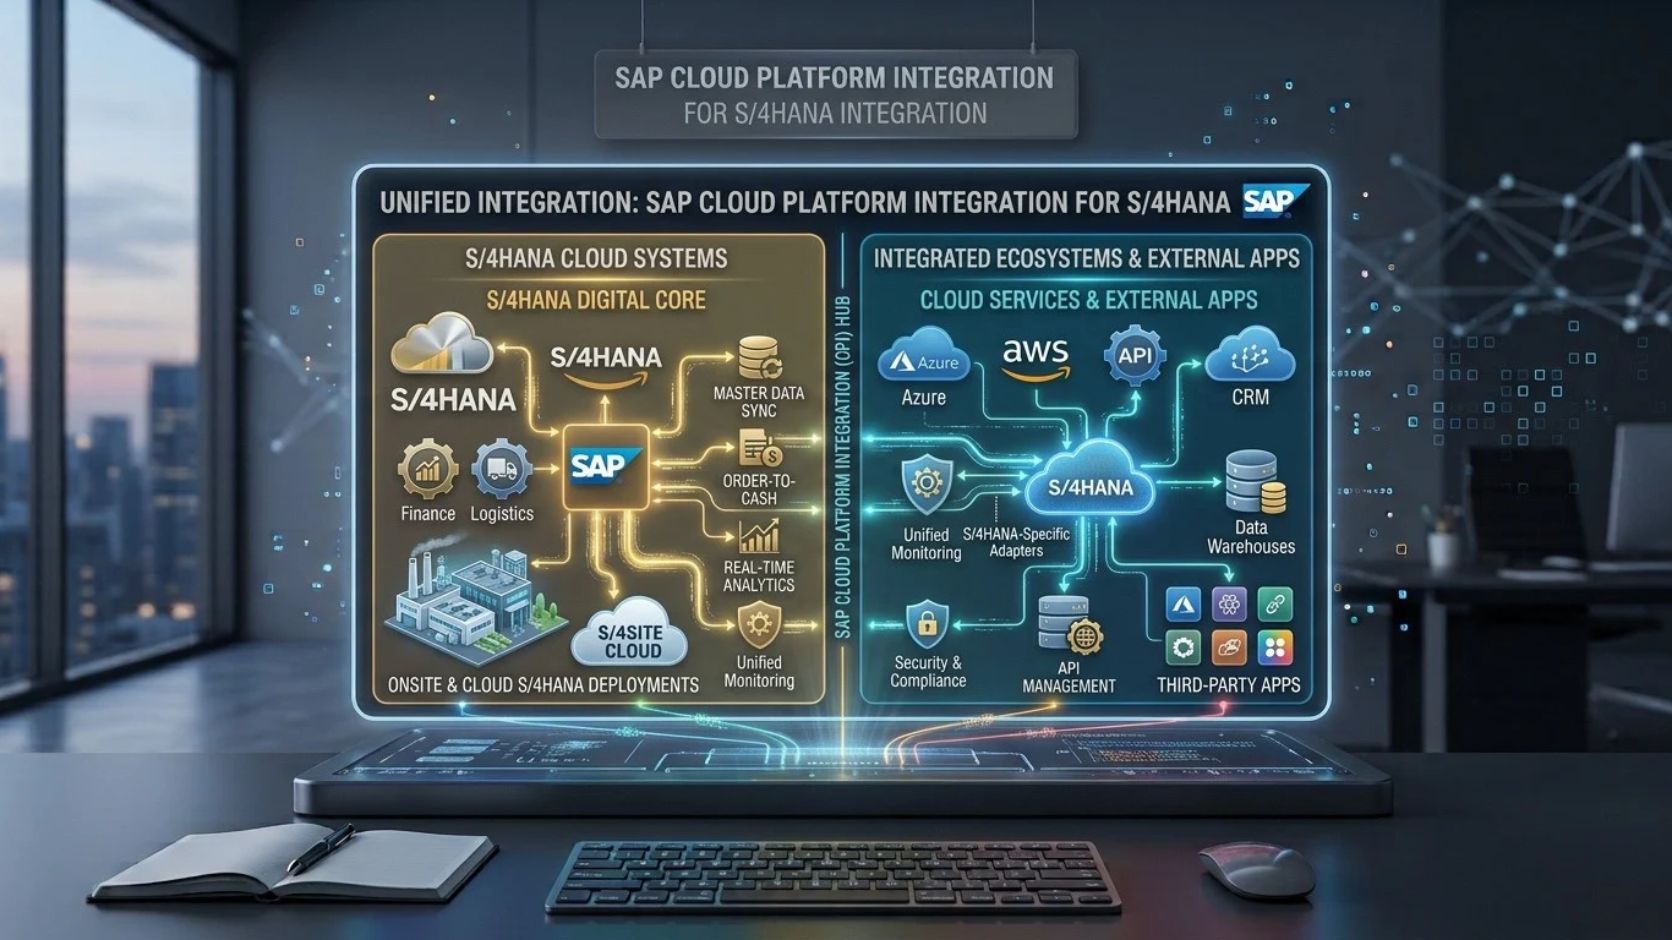
    SAP Cloud Platform Integration, now part of SAP Integration Suite, provides cloud-based integration capabilities for connecting SAP S/4HANA with SAP applications, third-party platforms, databases, APIs, and external services. It supports cloud-to-cloud, cloud-to-on-premise, and hybrid integration scenarios.

    For organizations using SAP S/4HANA, integration is important for exchanging business data across systems. Sales orders, customer records, product information, invoices, purchase orders, employee data, and financial information may need to move between multiple applications. SAP Cloud Platform Integration provides integration flows, adapters, mappings, routing, security controls, and monitoring features that help manage these exchanges.

    A key part of the integration environment is Destinations. Destinations provide connection information that applications and services can use to reach a target system. Depending on the scenario, connection information can include a URL, authentication method, and other connection properties.

    What Is SAP Cloud Platform Integration for S/4HANA?

    SAP Cloud Platform Integration for S/4HANA refers to using SAP’s cloud integration capabilities to connect SAP S/4HANA with other systems and services.

    SAP S/4HANA can operate in cloud, private cloud, or on-premise environments. Integration requirements therefore vary according to the deployment model, connected applications, security architecture, and business process.

    Cloud Integration uses integration flows, commonly called iFlows, to define how messages move between a sender and receiver. An integration flow can receive data, transform the message, apply business logic, route the message, and send the result to another system.

    For example, an organization may connect S/4HANA with Salesforce. A customer or sales process can generate data in one system, while the integration flow transforms and transfers the required information to the other system.

    Why S/4HANA Integration Is Important

    Modern enterprises rarely operate with a single business application. An S/4HANA environment may need to communicate with customer relationship management systems, human resources platforms, e-commerce applications, logistics platforms, banking services, data warehouses, and external partner systems.

    Integration allows these systems to exchange relevant information without requiring every application to communicate directly with every other application.

    For example, an order management process may involve:

    S/4HANA → API → Cloud Integration → External application

    The integration layer can transform data between different formats and protocols. This reduces the need to build separate point-to-point connections for every business process.

    S/4HANA integration can support common business areas such as finance, procurement, sales, manufacturing, supply chain, asset management, and order management.

    How SAP Cloud Platform Integration Connects with S/4HANA

    Cloud Integration can connect with S/4HANA through several communication technologies. The appropriate method depends on the S/4HANA deployment, available interfaces, security requirements, and business scenario.

    Common technologies include OData, REST, SOAP, IDoc, RFC, SFTP, and HTTPS-based APIs.

    OData is widely used for exposing and consuming business data through standardized web services. REST APIs are also common for modern application integration. SOAP remains relevant for systems and services that use web service interfaces.

    IDoc-based integration is commonly associated with SAP business processes and can be used where IDoc interfaces are available.

    The integration flow determines how the message is received, processed, transformed, and delivered.

    SAP S/4HANA Integration Architecture

    A typical architecture contains S/4HANA, SAP Cloud Integration, connectivity components, APIs or adapters, and external applications.

    The basic data flow can be represented as:

    S/4HANA → Cloud Integration → Transformation/Routing → Target System

    The reverse direction is also possible:

    External System → Cloud Integration → Transformation/Routing → S/4HANA

    Cloud Integration acts as an integration layer between applications. It can receive a message from a source system, process the payload, apply mappings or routing rules, and deliver the resulting message to the destination.

    For hybrid environments, additional connectivity components may be required to establish secure communication between cloud-based integration services and systems running inside an organization’s network.

    The Role of Destinations in S/4HANA Integration

    Destinations are important when applications need standardized connection information for accessing services or systems.

    A destination can define information such as the target endpoint, authentication configuration, and connection properties. This separates connection details from application logic and can simplify the management of connections across SAP environments.

    For example, an application may use a destination to identify an S/4HANA API endpoint without placing connection details directly into application code.

    Destinations can also be relevant when integrating SAP applications and services within the broader SAP BTP environment. The exact configuration depends on the service, authentication method, runtime, and integration architecture.

    Using centrally managed Destinations can make connection configuration easier to maintain when endpoints or authentication settings change.

    Integration Flows for S/4HANA

    An integration flow defines the processing logic for a particular integration scenario.

    A typical S/4HANA integration flow can contain a sender adapter, message processing steps, transformation logic, routing conditions, and a receiver adapter.

    For example, an integration flow can:

    1. Receive an S/4HANA message.
    2. Validate the message.
    3. Transform the payload.
    4. Apply routing conditions.
    5. Add or modify required information.
    6. Send the message to the target application.

    Integration flows can also include exception subprocesses for handling errors.

    The graphical design approach allows integration developers to organize these processing steps within a single integration artifact.

    S/4HANA API Integration

    APIs provide structured ways for applications to exchange data and functionality.

    S/4HANA provides APIs for many business objects and processes. Depending on the available interface, these APIs may use technologies such as OData or REST.

    Cloud Integration can consume an S/4HANA API, process the response, and deliver the required information to another application.

    For example, a business may need to transfer customer or sales information from S/4HANA to an external CRM platform. Cloud Integration can call the relevant API, transform the returned data, and send the required fields to the CRM system.

    API-based integration is especially useful when applications need standardized, controlled access to business data.

    Message Mapping Between S/4HANA and External Systems

    Different applications often use different data structures.

    S/4HANA may represent a customer, product, order, or invoice using a structure that differs from the target system. Message mapping converts the source structure into the structure expected by the receiver.

    Cloud Integration supports graphical message mapping and other transformation techniques.

    For example:

    S/4HANA Customer ID → CRM Customer Number

    S/4HANA Material Number → External Product ID

    S/4HANA Company Code → Target Legal Entity

    Mappings can include field transformations, value mappings, conditions, and other processing logic.

    Using Adapters for S/4HANA Integration

    Adapters provide communication capabilities between Cloud Integration and external systems.

    The required adapter depends on the communication protocol and application interface.

    HTTP-based adapters can be used for API communication. SOAP adapters support SOAP-based web services. SFTP adapters can exchange files with remote servers. IDoc-related adapters can support SAP IDoc scenarios.

    Selecting the correct adapter is important because it determines how the integration flow communicates with the connected system.

    Destinations and Secure Connectivity

    Security is an important part of S/4HANA integration.

    Connection configurations should use appropriate authentication and authorization mechanisms. Depending on the environment, these can include OAuth 2.0, basic authentication, certificates, or other supported security mechanisms.

    Destinations can store connection-related configuration so that applications can use managed connection information instead of embedding sensitive connection details directly in application logic.

    For hybrid integration, organizations may also use secure connectivity components to connect cloud services with internal SAP systems.

    Security configuration should consider authentication, authorization, encryption, certificate management, network access, and API protection.

    Cloud-to-Cloud S/4HANA Integration

    S/4HANA Cloud may need to communicate with other cloud applications such as SAP SuccessFactors, SAP Ariba, SAP Concur, Salesforce, or other SaaS platforms.

    Cloud Integration can provide the middleware layer between these applications.

    A typical cloud-to-cloud process can look like:

    S/4HANA Cloud → Cloud Integration → SaaS Application

    The integration flow can transform data and apply business rules before sending the message to the receiving application.

    This architecture helps separate application responsibilities from integration logic.

    Hybrid S/4HANA Integration

    Many organizations operate hybrid landscapes that include both cloud and on-premise systems.

    For example, S/4HANA may run on-premise while CRM, analytics, or other applications run in the cloud.

    In this situation, Cloud Integration can act as the central integration layer. Secure connectivity mechanisms can establish communication between the cloud integration environment and internal systems.

    A hybrid architecture may look like:

    On-Premise S/4HANA → Secure Connectivity → Cloud Integration → Cloud Application

    The reverse direction can also be implemented when an external cloud application needs to send information to S/4HANA.

    Error Handling and Monitoring

    Integration failures can occur because of authentication problems, unavailable endpoints, invalid payloads, mapping errors, network issues, or application-level errors.

    Cloud Integration provides monitoring capabilities that allow integration teams to inspect message processing and identify failed integrations.

    Exception subprocesses can be designed to handle errors within an integration flow. Logging and monitoring information can help identify the stage where processing failed.

    For example, if an S/4HANA API returns an HTTP error, the integration process can capture the error and handle it according to the configured integration logic.

    Effective monitoring is particularly important for business processes involving financial transactions, orders, inventory, and other time-sensitive data.

    Common S/4HANA Integration Use Cases

    SAP Cloud Platform Integration can support many S/4HANA scenarios.

    A sales integration may transfer customer and order information between S/4HANA and a CRM platform. A procurement integration can exchange supplier, purchase order, and invoice information with external procurement applications.

    Finance integrations can transfer accounting or payment-related information between S/4HANA and external financial systems. Supply chain integrations can connect S/4HANA with logistics, warehouse, transportation, and supplier platforms.

    Human resources scenarios can connect business processes across S/4HANA and SAP SuccessFactors when the required interfaces and integration content are available.

    The exact implementation depends on the APIs, interfaces, business processes, and deployment model used by the organization.

    Prebuilt Integration Content for S/4HANA

    SAP provides integration content for many common integration scenarios through SAP Integration Suite and related SAP content repositories.

    Prebuilt content can include integration flows, mappings, configuration guidance, and related artifacts.

    Using available content can reduce development effort when the required business scenario matches the provided integration package.

    However, organizations may still need to configure endpoints, authentication, mappings, value mappings, and business-specific requirements.

    Performance Considerations

    Integration performance depends on multiple factors, including message size, processing complexity, transformation operations, API response time, network latency, target-system capacity, and the number of messages being processed.

    Large payloads and complex transformations can require more processing resources.

    Integration designs should therefore use appropriate message structures and avoid unnecessary processing steps.

    API pagination, batching, asynchronous processing, and efficient mapping can be relevant depending on the specific S/4HANA integration scenario.

    Performance requirements should be tested using realistic message volumes and payload sizes rather than relying only on development-time testing.

    Best Practices for S/4HANA Integration

    A well-designed integration architecture should separate business logic, connectivity, transformation, and error handling where practical.

    Use standardized APIs and supported interfaces whenever they meet the business requirement. Keep credentials and sensitive connection information out of application logic. Apply appropriate authentication and authorization controls.

    Use clear naming conventions for integration flows and configuration artifacts. Monitor failed messages and maintain suitable exception handling.

    Destinations should be configured consistently according to the relevant SAP BTP and application architecture. Endpoint and authentication information should be managed securely.

    Testing should cover successful messages, invalid data, authentication failures, unavailable endpoints, mapping errors, duplicate messages, and other relevant failure conditions.

    SAP Cloud Platform Integration vs Point-to-Point S/4HANA Integration

    Point-to-point integration connects one application directly with another application. This approach can become difficult to maintain as the number of connected systems increases.

    Cloud Integration provides a centralized integration layer. Multiple applications can connect through standardized integration flows instead of creating separate direct connections for every system.

    For example, if S/4HANA needs to communicate with CRM, e-commerce, logistics, analytics, and supplier systems, a centralized integration platform can provide a common location for transformation, routing, monitoring, and security controls.

    This architecture can make integration management more structured as the application landscape grows.

    Frequently Asked Questions

    What is SAP Cloud Platform Integration for S/4HANA?

    SAP Cloud Platform Integration for S/4HANA uses SAP’s cloud integration capabilities to connect S/4HANA with SAP and non-SAP applications. It supports message processing, transformation, routing, API communication, security, and monitoring.

    Is SAP Cloud Platform Integration still called SAP CPI?

    SAP CPI is a commonly used name for SAP Cloud Platform Integration. The capability is now part of SAP Integration Suite and is generally referred to as Cloud Integration.

    What protocols can be used for S/4HANA integration?

    Depending on the scenario, S/4HANA integration can use technologies such as OData, REST, SOAP, IDoc, RFC, SFTP, and HTTPS-based APIs.

    What are Destinations in SAP integration?

    Destinations provide managed connection information for accessing a target system or service. Depending on the configuration, they can include an endpoint URL, authentication information, and other connection properties.

    Can Cloud Integration connect S/4HANA Cloud with third-party applications?

    Yes. Cloud Integration can connect S/4HANA with third-party applications when appropriate interfaces, APIs, adapters, authentication, and connectivity configurations are available.

    Can SAP Cloud Platform Integration connect to an on-premise S/4HANA system?

    Yes. Hybrid integration scenarios can connect cloud-based integration services with on-premise S/4HANA systems using appropriate secure connectivity architecture.

    Why are Destinations useful for S/4HANA integration?

    Destinations can centralize connection configuration and separate endpoint and authentication information from application logic. This can simplify connection management within supported SAP environments.

    How are S/4HANA integration errors monitored?

    Cloud Integration provides monitoring capabilities for integration message processing. Integration flows can also include exception subprocesses and error-handling logic to manage failures.

    Conclusion

    SAP Cloud Platform Integration provides a structured approach for integrating S/4HANA with SAP applications, third-party platforms, APIs, databases, and external services. Its integration flows support message transformation, routing, connectivity, security, and monitoring across cloud and hybrid environments.

    S/4HANA integration can use technologies such as OData, REST, SOAP, IDoc, SFTP, and HTTPS-based APIs according to the specific business scenario. Cloud Integration also supports centralized integration architecture, which can reduce the complexity associated with large application landscapes.

    Destinations are an important part of connection management in relevant SAP environments because they can provide reusable endpoint and authentication configuration. Combined with integration flows, APIs, adapters, mappings, monitoring, and secure connectivity, these capabilities provide a foundation for connecting S/4HANA with modern enterprise applications.

    Organizations planning S/4HANA integration should evaluate the deployment model, available APIs, communication protocols, security requirements, data mappings, monitoring needs, and business process requirements before implementing the integration architecture.

  • New Same-Day Stump Grinding Service Comes to Cincinnati

    New Same-Day Stump Grinding Service Comes to Cincinnati

    Valentine Services – Stump Grinding has introduced a new same-day stump grinding service for residential and commercial property owners in Cincinnati and surrounding communities, providing an additional scheduling option for customers seeking to address unwanted tree stumps, exposed surface roots and related property hazards.

    The new service is designed to accommodate property owners who need stump grinding completed on a shorter timeline. Same-day availability may be particularly relevant for homeowners preparing properties for landscaping projects, businesses maintaining commercial grounds, property managers addressing hazards and contractors working around construction or site-improvement schedules.

    Addressing Common Stump and Root Problems

    Tree stumps can remain after tree removal and may interfere with landscaping, mowing and other property improvements. Surface roots can also create uneven areas that may present tripping concerns or complicate future site work.

    Valentine Services – Stump Grinding provides stump grinding and stump removal services intended to address these conditions. The company’s service offerings include residential stump grinding, commercial stump grinding, root grinding, large stump removal, chip cleanup and site restoration.

    The company serves Cincinnati as well as communities throughout Northern Kentucky and the surrounding region.

    Company Response

    The introduction of same-day stump grinding expands the scheduling options available to customers who need service completed without an extended wait. Service availability can depend on location, workload, stump conditions and other project factors.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    Customers can request a free estimate and discuss project requirements directly with Valentine Services – Stump Grinding.

    Service Area

    Valentine Services – Stump Grinding serves customers throughout Cincinnati and nearby communities in Ohio and Northern Kentucky, including:

    • Cincinnati
    • Blue Ash
    • Mason
    • West Chester
    • Fairfield
    • Loveland
    • Hamilton
    • Florence
    • Covington
    • Erlanger
    • Burlington
    • Hebron
    • Nearby communities

    The company works with homeowners, businesses, property managers and contractors.

    Executive Quote

    “Same-day service gives property owners another option when a stump needs to be addressed on a tighter schedule,” said a representative of Valentine Services – Stump Grinding. “Our focus is on providing straightforward stump grinding and cleanup services while responding to the needs of customers throughout the Cincinnati and Northern Kentucky area.”

    Future Outlook

    Valentine Services – Stump Grinding plans to continue serving residential and commercial customers throughout the Cincinnati region while maintaining a focus on responsive scheduling, stump removal and property cleanup services.

    The company is licensed and insured and provides free estimates for stump grinding and related services.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company specializes in removing unwanted tree stumps, surface roots and tripping hazards for homeowners, businesses, property managers and contractors.

    Services include residential stump grinding, commercial stump grinding, root grinding, large stump removal, chip cleanup and site restoration. Valentine Services – Stump Grinding serves Cincinnati, Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, Hebron and nearby communities.

    The company is licensed and insured and offers free estimates and customer-focused service.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: https://www.513stumps.com/

  • Effective Shoulder Pain Solutions Now Available in Sydney

    Effective Shoulder Pain Solutions Now Available in Sydney

    Spine and Posture Care Chiropractor Sydney has introduced a new focus on shoulder pain care as part of its chiropractic services for patients experiencing musculoskeletal discomfort and movement-related concerns in Sydney.

    The Sydney chiropractic clinic provides individualized assessments and treatment programs designed to identify contributing factors behind pain and posture-related problems. Its approach combines spinal therapy, muscle work and rehabilitation to address physical issues that may contribute to ongoing discomfort.

    Addressing the Challenge of Shoulder Pain

    Shoulder pain can affect movement, daily activities and overall physical function. While symptoms may be felt primarily around the shoulder, contributing factors can involve surrounding muscles, the spine, posture or movement patterns.

    Spine and Posture Care’s chiropractors assess each patient’s presentation to help determine potential sources of discomfort before developing an individualized care plan. The clinic’s broader chiropractic services also address conditions involving the lower back, mid back and neck, along with sciatica, slipped discs, headaches and posture concerns.

    Individualized Chiropractic Care

    The clinic’s new shoulder pain service is based on a one-on-one care model. Treatment programs may incorporate spinal therapy, muscle work and rehabilitation depending on the individual’s assessment and needs.

    The approach is intended to provide patients with clear explanations of their condition and a structured treatment plan rather than relying on a one-size-fits-all approach.

    “Our focus is on understanding the factors contributing to a person’s pain and explaining those findings clearly,” said a representative of Spine and Posture Care. “By combining chiropractic care with muscle work and rehabilitation, we can develop an individualized approach that addresses both current symptoms and the factors that may contribute to them.”

    Sydney CBD Location

    Spine and Posture Care is located in Sydney City, conveniently positioned between Wynyard, Martin Place and Circular Quay. The clinic serves people seeking chiropractic care for pain, posture and related musculoskeletal concerns.

    The practice reports having received hundreds of five-star reviews from patients, reflecting its established presence in the local community.

    Company Background

    Spine and Posture Care is a chiropractic clinic in Sydney, NSW, focused on identifying contributing factors behind pain and posture-related concerns. Its chiropractors provide individualized treatment programs combining spinal therapy, muscle work and rehabilitation.

    Additional details are available at: https://share.google/O8QKN1qUIOwGNrFeU

    The clinic’s services include care for lower back, mid back and neck pain, sciatica, slipped discs, headaches, poor posture and shoulder pain. Its treatment model emphasizes one-on-one care, clear communication and evidence-based chiropractic treatment plans.

    Future Outlook

    The introduction of a dedicated shoulder pain focus expands the range of musculoskeletal concerns addressed by Spine and Posture Care. The clinic plans to continue providing individualized chiropractic programs for Sydney patients seeking support for pain, mobility and posture-related concerns.

    Patients can contact the clinic to discuss their concerns or arrange an appointment.

    About Spine and Posture Care Chiropractor Sydney

    Spine and Posture Care is a chiropractic clinic in Sydney, NSW, providing individualized care for pain and posture-related concerns. The clinic’s chiropractors combine spinal therapy, muscle work and rehabilitation to develop tailored treatment programs for each patient. The practice is located in Sydney City between Wynyard, Martin Place and Circular Quay.

    Media Contact

    Spine and Posture Care Chiropractor Sydney
    Email: Info@spineandposturecare.com.au
    Phone: +61 2 8040 9922
    Website: https://spineandposturecare.com.au/

  • Visa vs. Mastercard Issuing Programs: What API Builders Should Know

    Visa vs. Mastercard Issuing Programs: What API Builders Should Know

    For API builders, Visa and Mastercard issuing programs differ in certification flow, host messaging, fraud tooling, and sponsor bank expectations. Visa often centers on issuer processor validation and ADVT, while Mastercard typically leans on M-TIP and interface conformance. These differences affect launch scope, engineering effort, and compliance timelines. The practical tradeoffs are not always obvious at the start.

    Visa vs. Mastercard Issuing at a Glance

    At a high level, the card itself masks a similar issuing model across both networks: Visa and Mastercard each provide the network rails, operating rules, authorization standards, and brand acceptance framework that enable banks and fintech sponsors to issue payment cards.

    In market comparison, differences usually appear at the program layer rather than the branded card. Visa advantages may include issuer incentives, tokenization tooling, or regional acceptance patterns. Mastercard benefits may include specialized commercial products, analytics, or partner ecosystems.

    Issuing trends show convergence in digital-first provisioning, embedded finance, and real-time controls. Consumer preferences are influenced more by issuer rewards and app experience than network branding.

    Technology impacts center on APIs, fraud models, token services, and dispute workflows. Regulatory considerations vary by jurisdiction, while both networks maintain substantial global reach across merchants and cross-border payments.

    How to Choose Between Visa and Mastercard Issuing

    Choosing between Visa and Mastercard issuing typically starts with an assessment of network coverage differences across target markets and merchant categories.

    It also requires a comparison of program cost considerations, including scheme fees, processing expenses, and compliance overhead.

    API integration requirements should be evaluated as well, particularly with respect to implementation complexity, feature support, and compatibility with existing infrastructure.

    Network Coverage Differences

    Because acceptance reach directly affects authorization success and customer usability, network coverage should be evaluated by corridor, merchant category, and card-present versus e-commerce transaction mix rather than by brand reputation alone.

    Visa and Mastercard each offer broad global reach, but effective market penetration varies by country, acquirer routing, and merchant acceptance policies. In practice, regional preferences and consumer behavior can influence issuer performance more than headline card counts.

    API builders should map target geographies against MCC concentration, cross-border corridors, and wallet provisioning support. They should also compare transaction speeds in authorization messaging, fallback behavior, and offline acceptance resilience.

    Coverage can further diverge through technological advancements in tokenization, transit enablement, and push provisioning. Finally, regulatory differences, domestic scheme co-badging, and local processing mandates may alter acceptance patterns and routing outcomes materially.

    Program Cost Considerations

    Cost analysis should follow coverage analysis, since acceptance advantages can be offset by higher economics in the target mix. Selection should compare Visa and Mastercard program pricing across issuer fees, assessment rates, incentives, and ancillary charges. Effective evaluation emphasizes fee transparency and normalized cost structures, not headline discounts alone.

    1. Model transaction volume, geography, and card type to estimate financial impact accurately.
    2. Compare fixed versus variable fees to support budgeting strategies and expense management.
    3. Test incentive assumptions against renewal terms, thresholds, and compliance conditions affecting profit margins.
    4. Use competitive analysis to benchmark total network economics against target customer yields.

    Programs with similar acceptance can diverge materially in long-run unit economics. A disciplined framework helps quantify tradeoffs, identify hidden fees, and preserve margins as scale increases over time.

    API Integration Requirements

    While economics influence issuer selection, API integration requirements often determine implementation speed, control, and operational complexity. Visa and Mastercard both expose mature issuing capabilities, yet their API standards, event models, and authentication flows can differ enough to affect architecture decisions.

    Teams typically compare integration challenges around tokenization, webhooks, ledger synchronization, and dispute workflows.

    Evaluation also centers on compliance requirements, security protocols, and available documentation resources. Strong sandbox fidelity, clear versioning, and practical testing strategies reduce implementation risk and compress development timelines.

    Performance metrics such as authorization latency, webhook reliability, and rate-limit behavior directly influence user experience in card controls and transaction visibility. Builders should also assess support options, including solution engineering access, incident response paths, and regional certification guidance, because operational resilience depends as much on ecosystem responsiveness as on API design itself.

    From Stablecoin Balance to Card Network

    Stablecoin balances are useless at a checkout page that only accepts Visa or Mastercard — unless there’s a card layer in between. Crypto-funded virtual cards convert digital asset balances into network-accepted spending power, and the integration pattern is now well established. Providers offering a virtual card API for Nigerian businesses and similar markets have made crypto funding a standard option precisely because it matches how users in those markets already hold value.

    Visa Issuing Program Types Explained

    Visa issuing programs are structured around the intended funding model, authorization method, and cardholder use case. Common categories include debit, prepaid, credit, and commercial configurations, each with distinct settlement logic, ledger behavior, and controls.

    For API builders, evaluating Visa program features requires attention to tokenization, spend controls, dispute workflows, and regional processing rules. Implementation also depends on Visa compliance requirements, including KYC, AML, chargeback handling, and network certification.

    Relevant context may include Visa market trends and Visa technology innovations, especially for embedded finance and virtual cards.

    1. Debit programs link directly to deposit accounts.
    2. Prepaid programs use prefunded balances.
    3. Credit programs rely on revolving or charge terms.
    4. Commercial programs support business expense governance.

    Cross-network references such as Mastercard program benefits or Mastercard security protocols are comparators, not design inputs.

    Mastercard Issuing Program Types Explained

    Mastercard issuing programs are generally structured across consumer and commercial segments, with product formats including debit, credit, and prepaid.

    Program design also depends on the issuing model, particularly whether the arrangement uses sponsorship or a direct BIN structure.

    These categories define the operational, compliance, and settlement framework for Mastercard issuance.

    Consumer Vs. Commercial Programs

    Most issuing programs fall into two categories: consumer and commercial. Consumer programs prioritize user experience, customer support, and consumer benefits such as rewards visibility, dispute handling, and mobile controls.

    Commercial programs emphasize commercial flexibility, policy enforcement, reporting depth, and transaction efficiency across departments, vendors, and travel workflows.

    1. Consumer portfolios align features with market trends and engagement metrics.
    2. Commercial portfolios require stronger risk management, spend controls, and auditability.
    3. Both models must satisfy compliance requirements across onboarding, servicing, and monitoring.
    4. API builders should design for program scalability through modular controls and data access.

    Program architecture, therefore, differs by intended cardholder behavior, approval hierarchies, and servicing expectations.

    Mastercard issuers typically evaluate innovation strategies by balancing operational complexity, support costs, and ecosystem integration needs against measurable adoption outcomes and lifetime value.

    Debit, Credit, Prepaid

    Program type further shapes issuing architecture beyond the consumer-commercial split, particularly in how funds are sourced, risk is allocated, and authorization logic is applied.

    Debit programs pull from deposit balances, making debit card features, debit card security, debit card acceptance, and debit card overdraft controls central to real-time decisioning.

    Credit programs extend revolving credit lines, so issuers must model repayment behavior, credit card interest accrual, chargeback exposure, and underwriting thresholds.

    Product design often emphasizes credit card rewards and other credit card benefits, which affect interchange economics, ledger structure, and servicing requirements.

    Prepaid programs fund spending in advance, reducing credit exposure but introducing prepaid card limitations around reloads, cross-border access, and merchant categories.

    Even so, prepaid card flexibility supports controlled disbursements, budgeting, and specialized prepaid card usage across many use cases.

    Sponsorship And BIN Models

    Sponsorship and BIN structure determine how a Mastercard issuing program reaches the network, allocates compliance responsibility, and controls settlement flows. Mastercard programs typically operate through a licensed issuer, processor, or sponsor bank, depending on geography and regulatory scope.

    1. Bank sponsorship places principal membership, settlement, and scheme accountability with the sponsoring institution.
    2. Processor sponsorship models may bundle processing, program management, and network access under one commercial framework.
    3. Dedicated BIN allocation gives a program stronger product segmentation, reporting control, and customized authorization logic.
    4. Shared BIN management reduces setup complexity but can limit configuration flexibility, branding separation, and portfolio portability.

    For API builders, these choices affect integration design, ledger architecture, dispute operations, regulatory dependencies, and expansion strategy across multiple markets and partner structures over time.

    Visa vs. Mastercard API Integration

    While both networks expose modern APIs for issuer onboarding, transaction controls, tokenization, and reporting, Visa and Mastercard differ in developer tooling, authentication models, certification workflows, and regional product availability.

    An API capabilities comparison typically highlights Visa’s broader legacy interoperability and Mastercard’s modular service segmentation.

    Integration challenges overview usually centers on endpoint consistency, sandbox realism, webhook behavior, and partner dependency management across processors and sponsors.

    Developer resources availability varies by portal design, SDK coverage, and sample payload quality.

    Support documentation insights often show stronger implementation granularity in one market and better cross-product mapping in another.

    Performance benchmarks analysis focuses on latency, rate limits, and uptime transparency.

    Security standards evaluation emphasizes OAuth patterns, message signing, and key rotation.

    Customization options exploration and Future trends prediction increasingly favor event-driven architectures and embedded issuer orchestration layers.

    Visa vs. Mastercard Certification

    Although both networks impose rigorous approval gates before an issuer can move from development to production, Visa and Mastercard certification differ in test structure, mandatory artifact submission, host interface validation, and the division of responsibility among the issuer, processor, sponsor bank, and card manufacturer.

    1. Visa often emphasizes ADVT, CVN, and issuer host messaging validation.
    2. Mastercard commonly centers M-TIP, interface conformance, and profile-specific scenario testing.
    3. Both require documented compliance requirements, including EMV, personalization, dispute, and security controls.
    4. Responsibility allocation varies by program model, especially where processors pre-certify shared components.

    For API builders, the certification process affects launch timelines, vendor sequencing, and defect ownership.

    Network approval rarely depends on APIs alone; it also reflects card production readiness, transaction lifecycle accuracy, exception handling, settlement outputs, and sponsor bank signoff procedures.

    Visa vs. Mastercard Tokenization and Wallets

    Tokenization and wallet enablement introduce distinct implementation considerations across Visa and Mastercard issuing programs.

    Comparison typically centers on network token provisioning flows, lifecycle controls, and the scope of support for major digital wallets.

    These differences can affect integration design, credential-on-file strategy, and cardholder activation experience.

    Network Token Provisioning

    Network token provisioning replaces a card’s primary account number with a domain-specific token for digital wallets and card-on-file transactions, reducing exposure of underlying credentials and improving lifecycle management.

    For API builders comparing Visa and Mastercard issuing flows, emphasis typically falls on:

    1. Enrollment orchestration: issuer, token service provider, and risk-decision messaging.
    2. Token security features: cryptograms, device binding, domain controls, and detokenization restrictions.
    3. Token lifecycle management: suspension, resume, reissue, and automatic account updater interactions.
    4. Operational design: integration best practices addressing latency, retries, observability, and fallback paths.

    These mechanisms illustrate network tokenization benefits through lower fraud exposure and better credential continuity.

    They also affect user experience impact, regulatory compliance challenges, industry trends analysis, and future developments insights for scalable issuance platforms and processor architectures globally.

    Wallet Support Differences

    How Visa and Mastercard differ in wallet support is best understood through their token requestor ecosystems, wallet enrollment paths, and issuer control surfaces.

    Visa often emphasizes broader enablement across digital wallets through Visa Token Service, while Mastercard relies on MDES for comparable token lifecycle management and provisioning governance. Both support major OEM wallets, but issuer APIs, certification flows, and regional dependencies create different integration challenges.

    For API builders, these differences affect user experience, security features, and payment processing behavior.

    Visa may expose more granular issuer preferences in some markets, while Mastercard can vary by processor and wallet partner. Enrollment friction, transaction limits, and card art support also influence adoption rates and brand loyalty.

    The practical comparison depends on processor capabilities, issuer risk policies, and wallet-specific compliance requirements and operational readiness.

    Visa vs. Mastercard Virtual Cards

    Although both schemes support virtual card issuance, Visa and Mastercard differ mainly in provisioning models, control frameworks, and acceptance tooling rather than in the core ability to generate card-not-present credentials.

    API builders typically compare four areas:

    1. Provisioning: single-use, merchant-locked, and tokenized credentials shape virtual card features.
    2. Controls: spend limits, MCC rules, and expiration policies affect virtual card security and virtual card management.
    3. Operations: webhook design, metadata, and reconciliation fields influence virtual card tracking and virtual card integration.
    4. Commercial fit: supplier payments, subscriptions, travel, and ad spend define virtual card use cases, virtual card benefits, and virtual card adoption.

    In practice, neither network is categorically superior.

    Program design, processor capabilities, and issuer controls determine implementation quality, operational flexibility, and end-user acceptance across enterprise and consumer contexts.

    Where Visa and Mastercard Issuing Are Available

    Availability is determined less by the card brand itself than by issuer licensing, processor coverage, and local regulatory approval in each market. Visa locations and Mastercard regions often overlap, but actual issuing support depends on BIN sponsorship, settlement infrastructure, compliance scope, and processor certification.

    For API builders, global coverage should be assessed country by country rather than inferred from brand presence alone. Regional partnerships strongly influence launch speed, especially in Latin America, MENA, and parts of APAC where domestic schemes and cross-border rules shape program design.

    Market penetration varies by consumer debit, commercial credit, and prepaid categories, creating different availability factors for each use case. Network expansion and current issuing trends show both brands broadening acceptance footprints, yet operational readiness still hinges on local processor integrations, foreign exchange support, and regulatory sequencing.

    What Sponsor Banks Expect From Each Network

    Once market and processor coverage are confirmed, sponsor banks evaluate each network through an operational and risk-management lens. Their sponsor expectations typically center on network alignment with program economics, servicing models, and regional acceptance patterns.

    1. Compliance requirements: Banks assess rule clarity, certification scope, reporting obligations, and audit readiness.
    2. Risk management: They compare controls, exception handling, settlement predictability, and sponsor oversight tooling.
    3. Operational efficiencies: They examine implementation timelines, processor interoperability, tokenization support, and API maturity.
    4. Innovation priorities: They weigh product roadmaps, digital wallet enablement, data services, customer support responsiveness, and adaptability to market trends.

    In practice, neither network is universally preferred. Sponsor banks prioritize the option that best fits internal governance, launch discipline, partner capabilities, and long-term portfolio strategy within specific jurisdictions and use cases.

    Visa vs. Mastercard Fraud and Disputes

    Both networks provide mature fraud-control and dispute-management frameworks, but program differences emerge in rule structure, liability allocation, monitoring workflows, and chargeback operations.

    Visa typically emphasizes prescriptive controls through its risk programs, while Mastercard often structures oversight around comparable monitoring regimes and issuer accountability.

    For API builders, fraud prevention depends on configurable transaction monitoring, velocity controls, and authorization decisioning tied to risk assessment models.

    Visa and Mastercard each require adherence to compliance standards for reporting, evidence submission, and case timelines during dispute resolution.

    Their chargeback processes share common stages, yet reason-code taxonomies, representment procedures, and documentation expectations differ.

    Effective implementation therefore depends on network-specific fraud analytics, operational playbooks, and escalation paths.

    Strong customer support workflows also matter, especially when cardholders report unauthorized activity or contest merchant-originated transactions.

    Visa vs. Mastercard Pricing and Fees

    How Visa and Mastercard price an issuing program depends on the fee layers under review: network assessments, processing charges, cross-border markups, scheme compliance costs, and optional service fees tied to tokenization, fraud tools, or data products.

    1. Core fee structures combine interchange rates, switch fees, merchant discounts, and transaction costs.
    2. Pricing transparency varies by processor bundling, making hidden fees harder to isolate across annual fees, implementation, and reporting.
    3. Program economics shift with reward programs, customer support requirements, and value-added services licensed separately.
    4. International charges include foreign exchange spreads, cross-border assessments, and regional compliance surcharges.

    For API builders, comparison requires normalized pricing models, not headline rates.

    Effective review separates fixed, variable, and exception-based fees, then maps them against expected authorization volume, card geography, and settlement behavior.

    Which Network Strategy Makes Sense for You?

    Which network strategy fits best depends on program geography, cardholder use cases, acceptance requirements, and operational constraints. Selection should begin with network alignment to target corridors, merchant coverage, and customer segmentation.

    Teams typically compare brand perception, authorization performance, dispute workflows, and user experience across domestic and cross-border scenarios.

    Decision quality also depends on strategic partnerships with processors, sponsor banks, and BIN sponsors, since these affect technology infrastructure, launch speed, and scalability options.

    Regulatory compliance requirements may favor one setup over another in specific jurisdictions. Risk management considerations include fraud controls, chargeback patterns, and data access for monitoring.

    Market positioning matters as well: consumer rewards, commercial spend controls, or gig-worker payouts may map differently to Visa, Mastercard, or a dual-network approach balancing reach, resilience, and optionality over time.

    Frequently Asked Questions

    How Do Chargeback Representment Timelines Differ After Initial Dispute Submission?

    Representment timelines differ by network: Visa typically allows about 30 days after initial dispute submission, while Mastercard often permits 45 days. Exact windows depend on reason codes, regional rules, and issuer-acquirer workflows within the chargeback process, dispute resolution.

    Can One BIN Support Both Consumer and Commercial Card Products?

    Yes, one BIN can sometimes support both consumer cards and commercial cards, subject to network rules, processor capabilities, and issuer setup. BIN compatibility depends on product differentiation requirements, reporting, controls, and acceptance behavior across use cases.

    How Do Network Rules Affect Cross-Border Interchange Optimization Strategies?

    Network rules constrain cross border fees optimization by setting interchange rates, currency conversion requirements, and compliance standards. Effective strategies depend on regional regulations, merchant category treatment, card product classification, and permitted routing, settlement, and pricing structures.

    What Happens to Card Credentials During Issuer Processor Migrations?

    During issuer processor migrations, cardholder data and credentials are securely transferred, tokenized, revalidated, and mapped to new systems; migration challenges often involve issuer partnerships, security protocols, authorization continuity, lifecycle events, and minimizing disruption to cardholder transactions.

    Are Sustainability Card Materials Supported Equally Across Both Networks?

    Not equally; support for sustainable materials varies by issuer, manufacturer, and regional certification rather than network alone. Both enable eco friendly initiatives, but differences appear in card lifecycle requirements, procurement options, and measured environmental impact.

    Final words

    Visa and Mastercard issuing programs present similar goals but distinct execution paths. Visa often centers on issuer host validation and ADVT, while Mastercard leans on M-TIP and interface conformance. One may offer a cleaner fit for speed to launch; the other may better align with specific processor, sponsor bank, or geographic requirements. For API builders, the decision is less about brand preference than operational tradeoffs, where certification burden, fraud controls, and integration design directly shape program viability.
  • Digital Locks for Safer, Smarter Properties

    Digital Locks for Safer, Smarter Properties

    Locksmith Ninja Perth has expanded its residential security services to include digital lock installations, giving property owners in Northbridge and surrounding areas access to modern door-entry options designed around convenience and controlled access.

    The new service adds digital locking technology to the company’s existing range of locksmith solutions, which includes lock replacement, rekeying, key copying, lock repairs, emergency lockout assistance, break-in repairs and safe installations.

    Addressing Changing Property Security Needs

    As property owners consider alternatives to traditional keyed locks, digital locking systems can provide additional ways to manage access to a home or other property. Depending on the system selected, digital locks may support features such as fingerprint access and other smart-entry capabilities.

    For homeowners seeking to modernize an existing entry point, digital locks can offer an alternative to conventional keys while supporting day-to-day access management.

    Locksmith Ninja Perth Expands Its Service Offering

    Locksmith Ninja Perth now installs digital door locks as part of its broader approach to residential property security. The company works with customers to address different locking requirements, from routine lock changes and repairs to urgent situations involving lockouts or property damage.

    Digital lock installations may be particularly relevant for property owners looking to combine physical security with technology-based access features.

    Service Details

    Locksmith Ninja Perth provides a range of locksmith and home security services, including:

    • Digital door lock installation
    • Smart lock options, including fingerprint access
    • Lock replacement
    • Lock rekeying
    • Key copying
    • Lock repairs
    • Emergency lockout assistance
    • Break-in repairs
    • Safe installation

    The company provides services for property owners seeking to repair, replace or upgrade existing locking systems.

    Company Background

    Locksmith Ninja Perth provides locksmith and home security services for residential properties. Its services cover common security and access needs, including lock repairs, replacements, rekeying, key copying, emergency lockout assistance and safe installations.

    Additional details are available at: https://share.google/KhPbrzz2X4jIOOShr

    The company’s expanded digital lock offering adds smart-entry technology to its existing residential security services.

    Executive Statement

    “Digital locks provide property owners with another option when considering how they manage access to their homes,” said a representative of Locksmith Ninja Perth. “Our goal is to provide practical locksmith solutions that address both traditional security requirements and newer access technologies.”

    Future Outlook

    Locksmith Ninja Perth plans to continue supporting residential property owners with a combination of conventional locksmith services and technology-based security options. The addition of digital lock installations reflects the company’s ongoing expansion of services available to customers in Northbridge and surrounding areas.

    For more information about digital lock installations and other locksmith services, customers can contact Locksmith Ninja Perth directly.

    About Locksmith Ninja Perth

    Locksmith Ninja Perth provides home security and locksmith services, including lock replacements, rekeying, key copying, lock repairs, emergency lockout assistance, break-in repairs and safe installations. The company also installs digital door locks with smart features such as fingerprint access.

    Media Contact

    Locksmith Ninja Perth
    Email: admin@lockninja.com.au
    Phone: +61 413 320 222
    Website: https://www.locksmithninjaperth.com.au/